Lately, discussions about utilizing 401(k) funds for home purchases have gained traction, especially as potential buyers seek creative ways to overcome affordability hurdles. While the allure of accessing retirement savings might be tempting, it’s essential to approach this possibility with caution.
Before considering this route, it’s critical to evaluate all available options and consult with a financial advisor to understand the risks involved. Many people might find the prospect of leveraging their retirement savings for immediate needs appealing—but is it truly a sound strategy?
Why Accessing Your 401(k) Might Be Tempting
According to data from Empower, many individuals have accrued substantial balances in their 401(k) accounts. The median balance for those in their 40s to 60s stands at six figures, making the idea of funding a home purchase from this pool of savings appealing. This isn’t just an abstract notion; for many potential homebuyers, their 401(k) accounts represent the bulk of their savings, often overshadowing other financial resources.
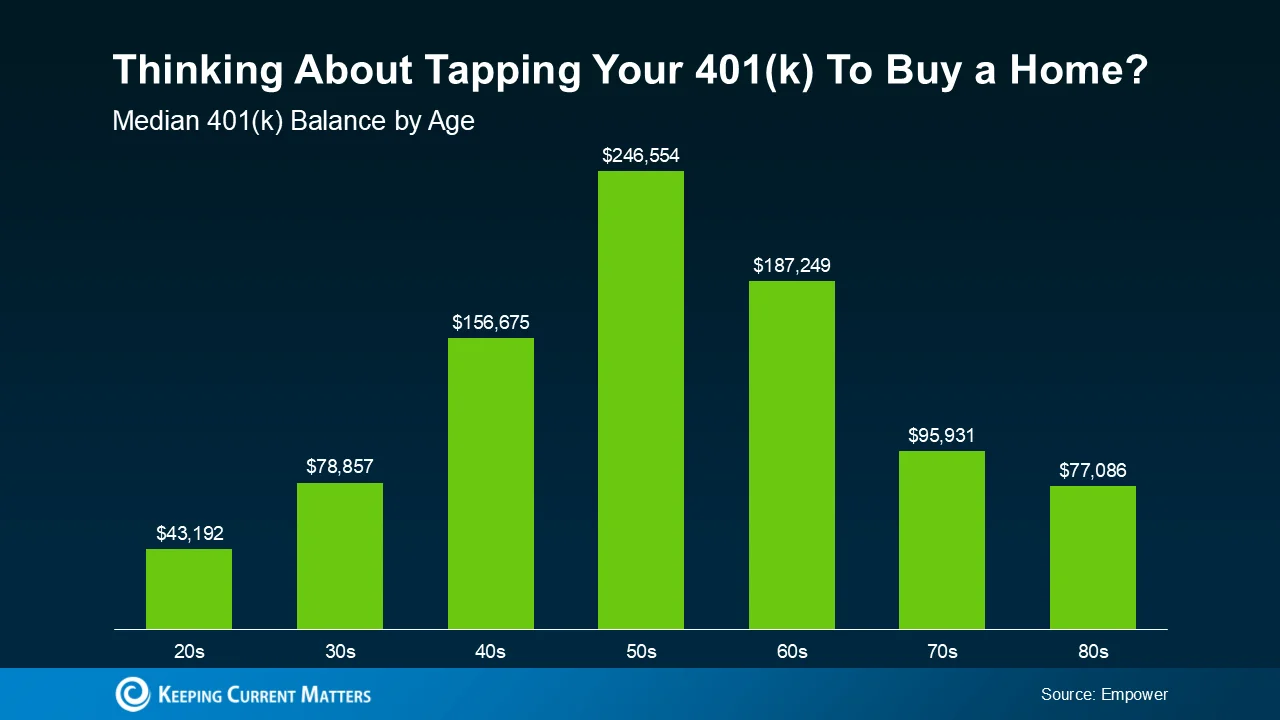
However, drawing from retirement savings to finance a home can entail penalties and financial setbacks down the road. Tapping into these funds may seem like an immediate solution for rising home prices, but it overlooks the longer-term implications. The potential penalties for early withdrawal can drastically diminish the expected benefits. It’s prudent to explore other avenues for your down payment before making a final decision. As Redfin aptly states:
“While tapping into your 401(k) can be an option, doing so poses significant risks, including early withdrawal penalties and the loss of potential investment growth.”
Engaging a financial advisor can help you weigh the benefits against the drawbacks. Important insights from Bankrate can shed light on this consideration. They emphasize that while the short-term gratification of homeownership is appealing, it shouldn’t come at the cost of long-term financial stability.
Alternative Financing Avenues
Your retirement savings aren't the only route available for securing a home. The options available to buyers have diversified in recent years, reflecting the changing dynamics of the property market. Redfin highlights several other financing options you might want to explore first:
- Low and No-Down Payment Options: Programs such as FHA loans can allow qualified buyers to make down payments as low as 3.5% based on their credit standing. These programs are designed to help make homeownership achievable for a broader demographic, particularly first-time buyers.
- Down Payment Assistance Programs: Both national and local initiatives may help mitigate your upfront costs for a down payment or closing fees. Such programs often target low-to-moderate income buyers and can significantly improve access to housing.
These alternatives may ease some of the burdens of affordability. In fact, exploring these options can reveal opportunities that could make the whole process smoother. The competitive nature of the market may necessitate creativity in financing.
Strategizing Your Next Steps
Regardless of the pathway you choose, consulting with a financial specialist should be your first step. Successful buyers typically develop a strategic plan in collaboration with seasoned professionals before embarking on their journey to homeownership. This proactive approach can prevent costly mistakes that come from acting on impulse or a lack of knowledge. According to NerdWallet:
“Understanding the risks associated with a 401(k) loan at the outset is vital, even if you believe it’s the best option.”
Many new buyers get lost in the excitement of home shopping, overlooking the intricacies of financing. But buying a home isn’t a race. It’s a significant investment, and a strategic approach is necessary. By getting a clear picture of your financial standing, you're setting up for longer-term success.
Implications and Future Outlook
As home prices continue to fluctuate and affordability remains a concern, discussions around unconventional methods of financing—like using 401(k) funds—will likely persist. What this means for you as a buyer is the necessity for diligence; knowing your options isn’t just a nicety, it’s essential.
The trend of tapping into retirement accounts for immediate needs signifies a broader debate about the balance between immediate gratification versus long-term security. Many individuals find themselves at a crossroads, weighing the desire for homeownership against the potential risks of their financial future. (And this is the part most people overlook.)
In conclusion, affordability may be a concern, but relying solely on your 401(k) isn’t the only strategy available for home buyers. If you're contemplating using these savings for a down payment, it's crucial to assess all your options and engage a trusted financial advisor who can tailor a plan to your financial situation and aspirations. Overall, these decisions require careful thought—don’t let short-term pressures dictate your long-term financial health.